Licensed life insurance agent · Purity Wealth Group

Keep more of what you earn. Protect what you've built.

Tax-efficient strategies for families, high earners and business owners, explained in plain English.

I help people use indexed universal life, annuities and executive bonus plans to build tax-advantaged retirement income, protect their families, and reward the people who keep their business running.

Based in Marin County, CA Licensed in CA Education-first, no-pressure calls 45 years combined team experience
How an indexed account credits

Participate in the upside. Skip the down years.

Index returnCredited (0% floor, 10% cap)

Hypothetical illustration only, not the performance of any product. Caps, floors and participation rates vary by carrier and policy and can change.

What I help with

Four strategies, each built on a section of the tax code.

Every recommendation starts with your goals and your tax picture. These are the tools I use most.

IRC §7702

Indexed Universal Life & tax-free retirement

Permanent life insurance with cash value tied to a market index. Growth is credited with a floor, so a down market doesn't erase your gains.

  • Tax-deferred cash value growth
  • Tax-advantaged access through policy loans
  • No IRS contribution limits like a 401(k) or IRA

Good fit: high earners who've maxed out traditional retirement accounts.

IRC §162

Executive bonus plans

Your business pays the premium on a policy owned by a key employee (or you). The bonus is generally deductible to the business, and you choose who participates.

  • Reward and retain key people
  • No ERISA testing or IRS filing
  • Optional vesting to keep talent in place

Good fit: owners with meaningful annual tax liability and people they can't afford to lose.

IRC §72

Annuities

Fixed and fixed-indexed annuities protect principal from market loss and can turn savings into income you can't outlive.

  • Principal protection from market declines
  • Tax-deferred growth
  • Optional lifetime income riders

Good fit: people within 10–15 years of retirement who want certainty.

IRC §101(a)

Life insurance & legacy planning

Term and permanent coverage that replaces income, pays off debt and passes wealth to the next generation with a generally income-tax-free death benefit.

  • Family income protection
  • Estate liquidity and wealth transfer
  • Business succession and buy-sell funding

Good fit: parents, business partners, and anyone with people depending on them.

How it works

From first question to a written plan.

STEP 1 · 2 MIN

Answer a few questions

A short check below tells us whether a strategy call makes sense for you right now. No sensitive information required.

STEP 2 · 30 MIN

Strategy call

We talk through your goals, taxes, timeline and what you already have in place. You'll leave understanding your options, whether or not we work together.

STEP 3 · ~1 WEEK

Your custom design

I shop the carriers, model a few scenarios, and walk you through illustrations side by side before you decide anything.

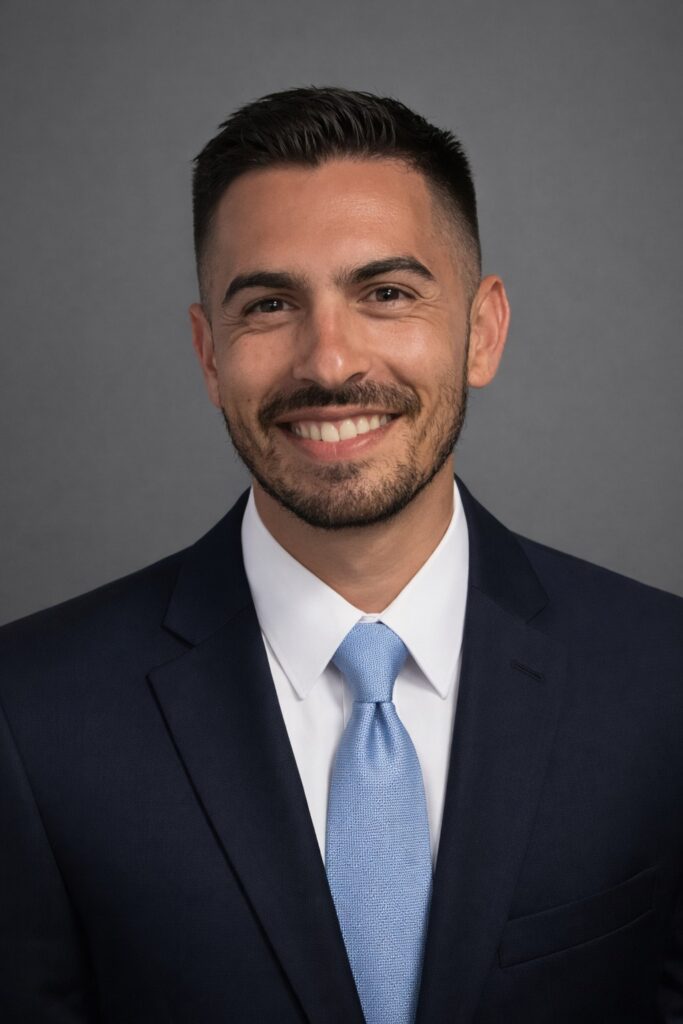
Nico Spann, licensed life insurance agent
About Nico

I've been a business owner. I plan like one.

Before I became a licensed life insurance agent, I spent more than a decade founding and running companies. I've made payroll, dealt with surprise tax bills, and wondered how to keep my best people. That's the lens I bring to every client conversation.

Today I work with Purity Wealth Group, a Bay Area brokerage that puts education first. We aren't tied to one insurance company, so I can compare carriers and recommend what fits you.

“If you can't explain it on a napkin, you shouldn't buy it.”
Education firstLifetime relationshipsLong-horizon planningTrust that compounds
Book a strategy call

Let's see if we're a fit.

A few quick questions. If a call makes sense, you'll pick a time on my calendar right away.

  • Free 30-minute call by phone or Zoom
  • No obligation and no sales pressure
  • Your answers stay private
Questions

Common questions.

Is IUL an investment?

No. An IUL is a life insurance policy. Your cash value isn't invested in the market; it earns interest based on an index's performance, subject to a cap and a floor. That's why a market drop doesn't reduce your credited value, and also why your upside is limited.

How is money from a policy "tax-free"?

Cash value grows tax-deferred, and you can generally access it through policy loans, which aren't treated as taxable income while the policy stays in force. Loans accrue interest and reduce the death benefit, so the policy has to be designed and managed carefully. I'll show you exactly how this works in your illustration.

Who pays for an executive bonus plan?

The business pays the premium as a bonus, which is generally tax-deductible to the business. The employee reports the bonus as income; many plans include a second "double bonus" to cover that tax. Your CPA should confirm the treatment for your business.

Do I have to live nearby?

No. Calls happen by phone or Zoom. Product availability depends on your state, and I'm licensed in CA.

What does the strategy call cost?

Nothing. I'm compensated by the insurance carrier only if you choose to buy a policy, and I'll be upfront about how that works.

Nico Spann Pure Strategies. Lasting Wealth.

Nico Spann is a licensed life insurance agent, License #4399467, licensed in CA. Insurance products are offered through Purity Wealth Group. Products and features are not available in all states.

Indexed universal life insurance is not a security or an investment in the stock market. Index-linked interest is subject to caps, participation rates and floors, which vary by carrier and policy and may change. Policy loans and withdrawals reduce cash value and death benefit, accrue interest, and may cause the policy to lapse; a lapse with an outstanding loan can create a taxable event. Guarantees are backed by the financial strength and claims-paying ability of the issuing insurance company.

This site is for educational purposes and isn't tax, legal or investment advice. Consult your own tax professional or attorney about your situation.